Learn
Does homeowners insurance cover basement or crawl space water damage?
Sometimes. It depends almost entirely on where the water came from. What is usually covered, what usually is not, and how to give a claim its best chance.
The short version
- Sudden, accidental water from inside the house (a burst pipe, a failed water heater) is usually covered.
- Groundwater seepage, surface flooding and long-term leaks usually are not, unless you have flood insurance or a water backup endorsement.
- Damage is covered more often than the cause: the policy may pay to dry and rebuild but not to waterproof.
- Photograph everything, call the same day, and get the drying started; waiting can void the claim.
We are waterproofers, not insurance agents, and every policy is different. This is the pattern we see on Louisville jobs. Read your own policy and ask your agent; the words below will help you ask the right questions.
Usually covered: sudden and accidental, from inside
Standard homeowners policies are built around sudden, accidental events. A pipe bursts, a water heater lets go, a washing machine hose fails, an upstairs tub overflows. The water damage to the basement, its contents and the finishes is typically covered, minus the deductible. The failed pipe or appliance itself often is not; the policy pays for what the water ruined, not for the part that broke.
Usually not covered: water from the ground or the sky
- Groundwater seepage through walls, floors and the cove joint, which is the most common wet basement in Louisville, is excluded on most standard policies.
- Surface water and flooding, meaning rain running in from outside, creek or river flooding, or water pooling against the house, is excluded and only covered by a separate flood policy through the National Flood Insurance Program or a private flood carrier.
- Sewer and drain backup, including a sump pump failing, is excluded unless you added a water backup or sump pump overflow endorsement. It is inexpensive and worth asking for.
- Gradual leaks and long-term moisture, including mold from a damp crawl space, are treated as maintenance and excluded almost everywhere.
Damage versus cause
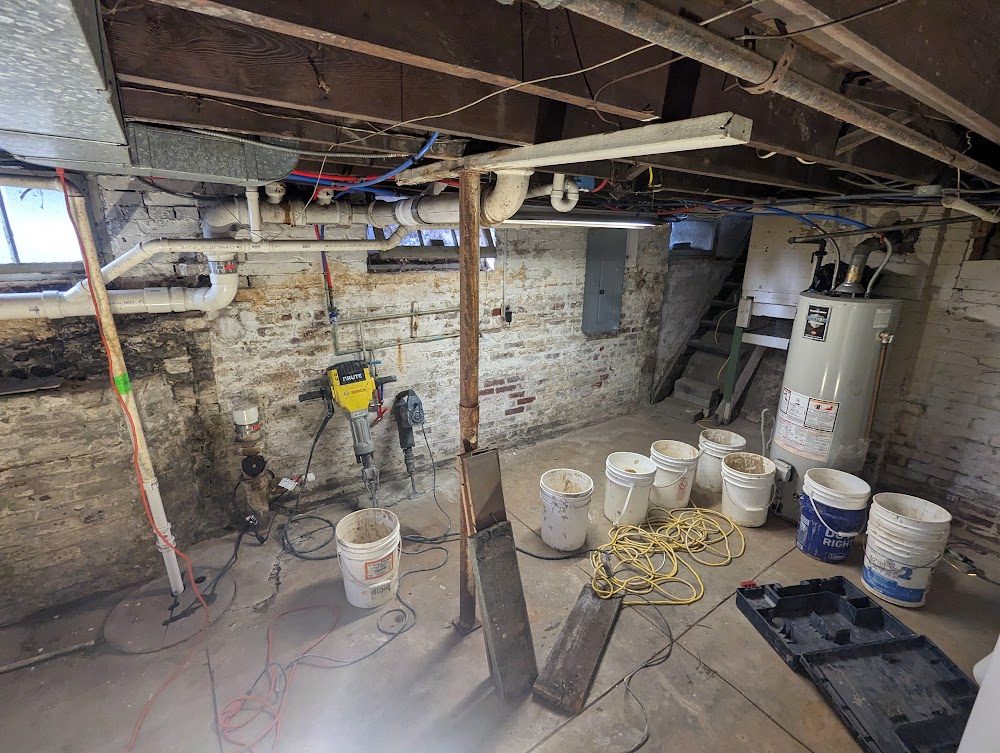
Even when a loss is covered, the policy pays to repair the damage: drying, tearing out and replacing finishes, replacing contents. It does not pay to make the basement waterproof so it does not happen again. That work, the drainage, the sump, the wall system, is on the homeowner. This surprises people after a covered sump failure: the carpet is paid for, the battery backup is not.
How to give a claim its best chance
- Photograph and video everything before you move it: the water line, the source, each damaged item, the serial plates on ruined appliances.
- Call the insurer the same day. Most policies require prompt notice, and a delay that lets mold grow can be used to reduce or deny the claim.
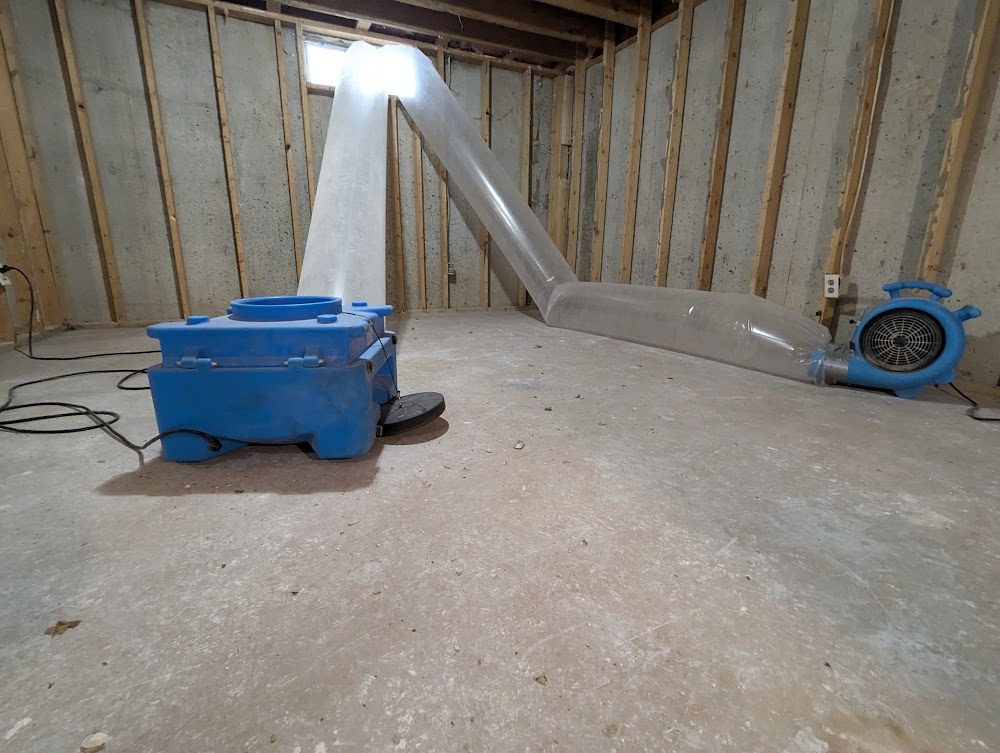
- Stop the damage from getting worse. Policies require you to mitigate: shut the water off, get the water out, start drying. Keep receipts for pumps, fans and dehumidifier rentals; they are usually reimbursable.
- Keep the ruined material until the adjuster has seen it or has told you in writing it can go. Bag it, list it, photograph the bags.
- Get the cause in writing from whoever fixes it. A plumber's invoice that says “burst supply line” is the document the adjuster wants.
The endorsements worth asking your agent about
- Water backup / sump overflow: covers sewer backups and sump pump failures. Usually a small annual cost.
- Flood insurance: the only thing that covers surface and river flooding. Required in mapped flood zones, available almost anywhere, and in Louisville the low-lying areas near the river, Beargrass Creek and the Salt River are the ones to think about.
- Service line coverage: the water and sewer lines between the street and the house, which are otherwise yours to repair.
Where that leaves a wet basement
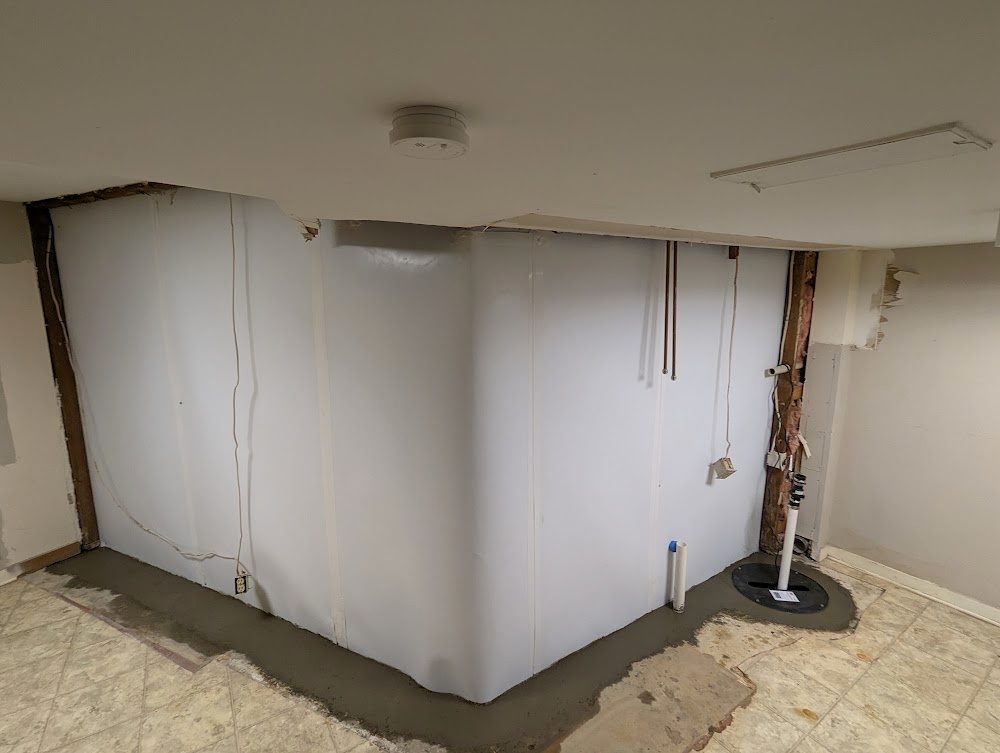
For most Louisville homeowners with a basement that seeps after heavy rain, insurance is not the answer and never was. The answer is fixing the drainage so it stops. The cost guide has typical ranges, and the inspection and written price are free, so you can decide with real numbers rather than a hope about the policy.
Keep reading
More from the crew
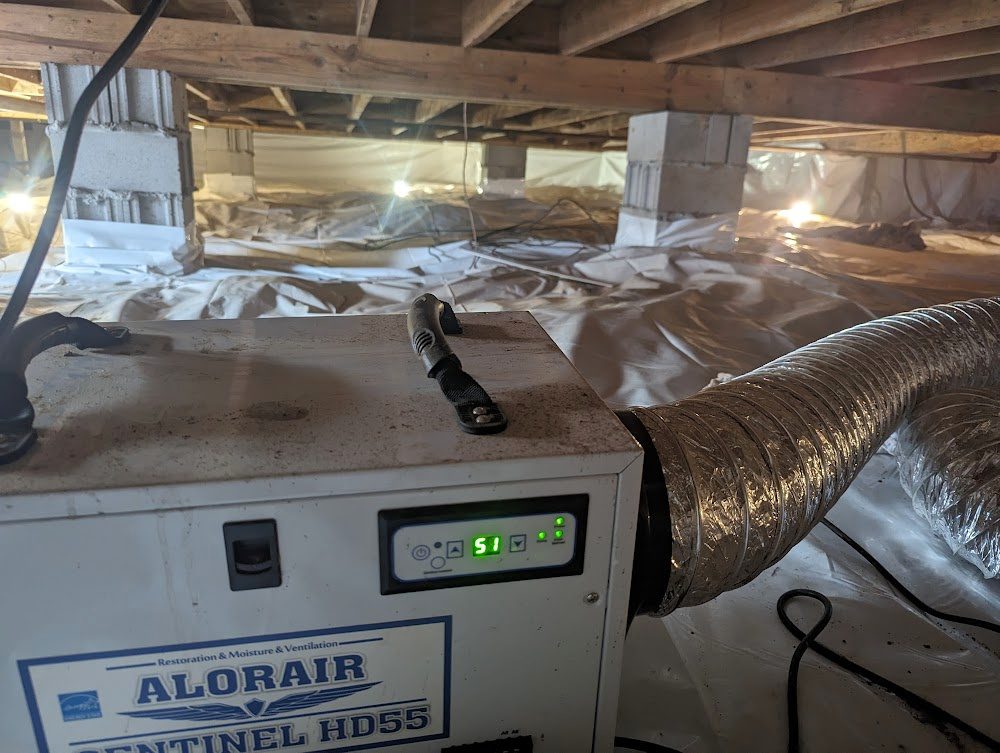
What humidity should a crawl space be?
Keep a crawl space under 60% humidity. Why Louisville crawl spaces run wet every summer and the fix in order: water, ground, vents, then the dehumidifier.
Read the article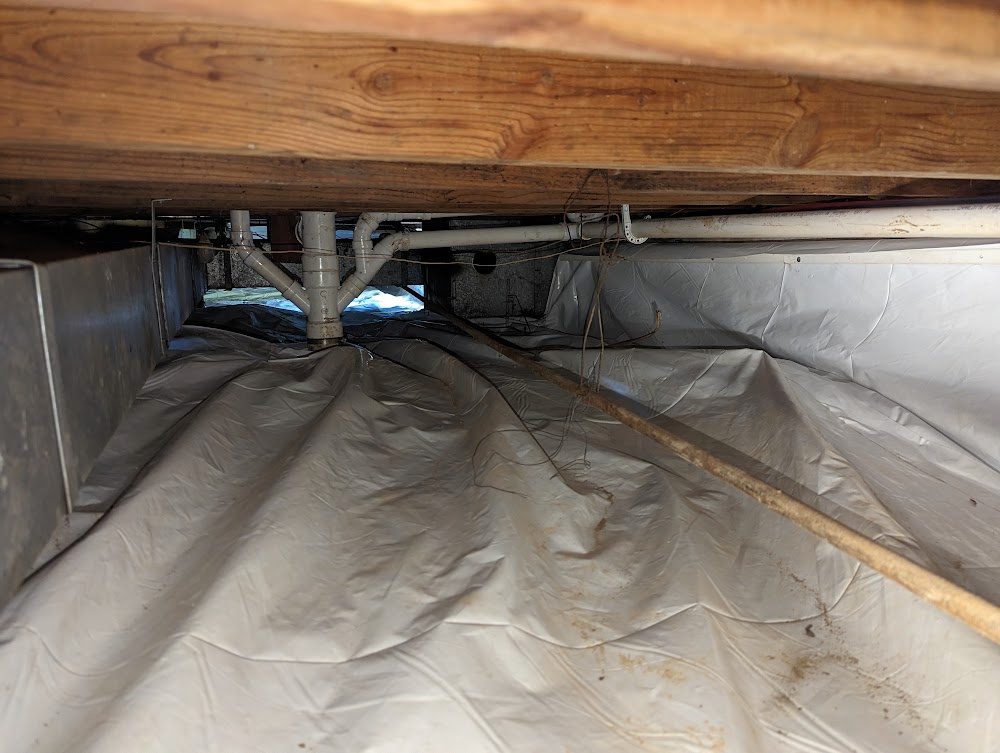
Crawl space encapsulation vs. vapor barrier
A vapor barrier covers the floor; an encapsulation seals the whole crawl space and adds a dehumidifier. How to tell which your Louisville crawl space needs, and why drainage comes first.
Read the article
Why your sump pump keeps running
A sump pump that cycles after heavy rain is normal in Louisville. One that runs on dry ground usually means a bad discharge line, a failed check valve, a stuck float or a worn pump. How to check each.
Read the articleQuestions
Asked about this
Still have a question? Call the office, Monday to Saturday, 9:00 AM to 5:00 PM.
Does homeowners insurance cover a sump pump failure?
Not on a standard policy. It is covered if you added a water backup or sump pump overflow endorsement. Check your declarations page for those words, and ask your agent to add it if they are not there.
Is water seeping through basement walls covered?
Almost never. Groundwater seepage is treated as a maintenance and drainage issue and is excluded on standard homeowners policies. The fix is waterproofing, and the inspection for that is free.
Does insurance cover mold in a crawl space?
Rarely. Mold from ongoing moisture is excluded as gradual damage. Mold that results from a covered sudden loss, like a burst pipe, may be covered up to a mold limit in the policy, which is often small.
Will filing a water claim raise my premium?
It can, and some carriers count water claims heavily. For a small loss close to the deductible it is worth comparing the payout to the likely premium change with your agent before filing.
Related services
What we do about it
Water Mitigation and Dry-Out
Fast extraction and drying after a flood or leak, then the repair that stops a repeat.
Learn more
Basement Waterproofing
Interior drainage, sealed walls and a sump that carry the water out after heavy rain.
Learn more
Sump Pump Installation and Replacement
Sealed basins, quality pumps, battery backup: the last line of defense, done right.
Learn moreFree estimate
Want a technician to look?
Tell us what you are seeing. A technician calls back during business hours and books a time to come out. Free, no obligation, written price.
- Photos and a plain explanation of the cause
- Written scope and price
- Lifetime transferable warranty on our work